

Best Budget Household Essentials for Families in 2026
Table of Contents
- Why Budget Household Essentials Matter for Families
- Family Budget Categories That Cover Every Essential
- The Best Budget Household Essentials to Buy First
- Understanding Your Monthly Household Expenses
- Ways to Save Money on Household Supplies
- How to Use a Household Budget Calculator
- Family Size and Life-Stage Variations in Essentials
- Building a Realistic Starter Budget and Shopping Plan
- Frequently Asked Questions
Last Updated: October 21, 2026
Why Budget Household Essentials Matter for Families
Running a household is a business with no CFO. Money leaves every month for rent, food, power, and cleaning supplies, with no report on where it went.
Here is the uncomfortable truth most budgeting guides skip: your fixed costs are not the problem. Rent and insurance are hard to move.
Below, we break down the categories, the items worth buying first, and a starter plan you can run this month.
Family Budget Categories That Cover Every Essential
A workable family budget splits into a handful of buckets. The Consumer Financial Protection Bureau's budgeting guidance recommends tracking spending by category before setting limits, because you cannot cut what you have never measured. Most families need these:
- Housing: rent or mortgage, property taxes, household repairs
- Utilities: electricity, water, gas, internet
- Groceries and food expenses: the weekly shop plus household supplies
Those are your essential expenses. Everything else is discretionary.
Needs vs. Wants: Sorting Your Essentials List
Needs keep the household running: food, shelter, power, medicine, cleaning supplies. Wants improve life but can wait a month: a second blender, decorative storage, a new phone stand. The sorting rule is simple: if the item breaks and the household stops functioning, it is a need; if you shrug, it is a want.

A common mistake is labeling a want as a need because it is on sale. A discount does not change the category.
Where Insurance and Health Care Fit In
Insurance is the category families underfund most. Health, home, and auto premiums belong in the fixed column, not the flexible one. Treat them as untouchable when you trim, and fund them before anything discretionary. Skipping coverage to free up cash is the one trade that can wipe out a year of savings in a single event.
The Best Budget Household Essentials to Buy First
Most budgeting guides tell you to track categories. That is useful, but it does not answer the question families actually type into a search bar: what should I buy first when money is tight?
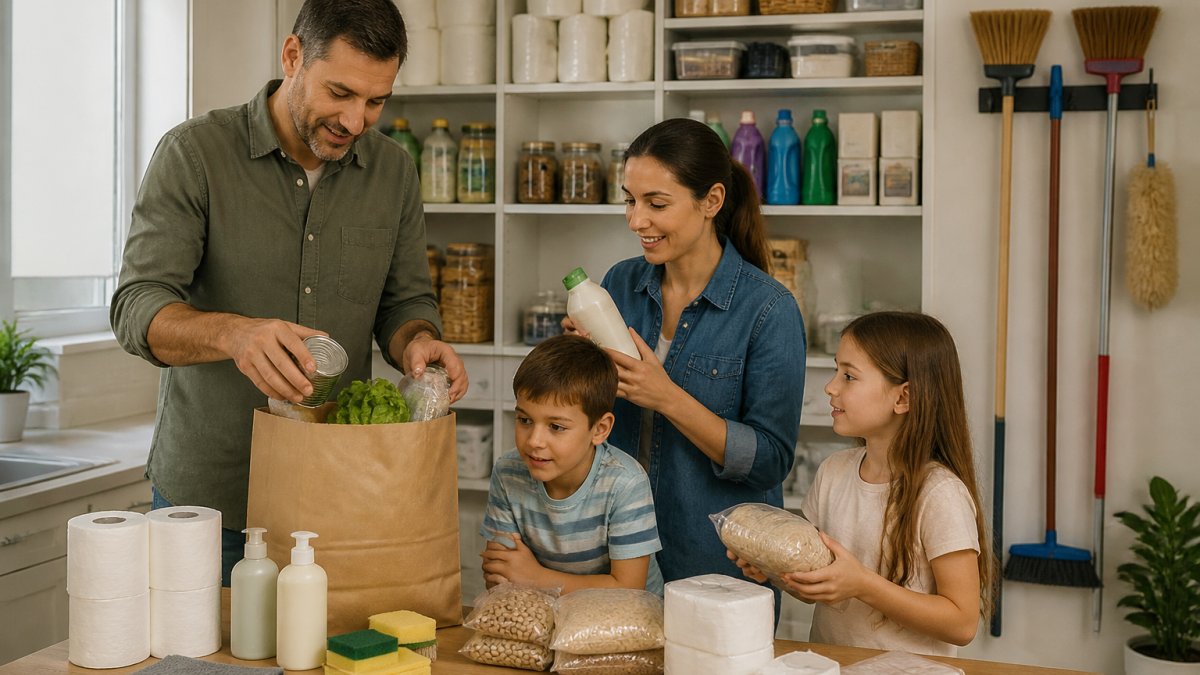
Priority 1: Items That Stop Recurring Waste
These pay for themselves fastest because they replace something you buy again and again.
- Reusable storage containers (glass or BPA-free plastic): A set of three to five stackable containers typically runs $15 to $30. They replace plastic wrap, foil, and takeout containers, and keep leftovers edible long enough to actually eat. Cost-per-use drops below disposables within weeks.
- Refillable spray bottles and concentrated cleaner: A concentrate plus two refillable bottles often costs less than two ready-to-use spray bottles, and one concentrate makes multiple bottles. It is one of the few swaps where the cheaper upfront option is also the lower-waste one.
- Wall-mounted mop and broom organizer: $20 to $30. Holds brooms, mops, and dusters off the floor so they dry properly and last longer. A damaged broom gets replaced; a hung one does not.
Priority 2: Items That Replace a Recurring Purchase
These cost more upfront but remove a line item from your monthly spending.

- Portable blender or countertop blender: A basic personal blender runs $20 to $40; a mid-range countertop model $40 to $80. If your family buys smoothies out even twice a week, the personal blender pays for itself within a month or two. Check motor wattage and whether replacement cups or blades are sold separately.
- Coffee maker or kettle plus a travel mug: For families that buy coffee out, a $20 to $40 drip maker or kettle plus a $10 to $15 insulated mug replaces a daily $3 to $5 habit. The mug matters as much as the brewer; a good one keeps coffee hot through a commute.
- Lunch containers and a lunch bag: A set of divided containers plus an insulated bag typically costs $20 to $35. This is the highest-return purchase for school-age children and adults who buy lunch at work.
Priority 3: Items That Protect What You Already Own
These do not replace a purchase, but they extend the life of things you have already paid for.
- Shoe rack or boot tray: $15 to $30. Keeps wet shoes off floors and extends the life of both shoes and flooring.
- Drying rack: $15 to $25. Air-drying clothes and delicates reduces dryer wear and energy use.
- Desk phone stand: $10 to $15. Prevents cracked screens and keeps a phone off the kitchen counter where it gets splashed.
How to Compare Cost-Per-Use
A simple rule: divide the purchase price by the number of times you expect to use the item in a year. A $25 organizer used daily costs pennies per use. A $10 gadget used twice costs more per use than a $40 version used weekly. The cheaper sticker price is not always the cheaper item.
A Starter Basket Under $100
If you are starting from scratch, a practical first basket is: one storage container set ($15 to $30), one pack of microfiber cloths ($10 to $20), one wall-mounted organizer ($20 to $30), and one phone stand ($10 to $15). That covers waste reduction, cleaning, storage, and desk protection for roughly $55 to $95 before tax. Add the blender or lunch containers in month two once the first basket has proven its value.
Understanding Your Monthly Household Expenses
Monthly household expenses are the total of everything your family spends to keep the home running, from rent and utilities to groceries, insurance, and supplies. Tracking them starts with three months of bank and card statements sorted into the categories above. Most families find two surprises: groceries and household supplies are usually one blended line, hiding how much goes to cleaning products and paper goods, and small online orders add up quietly.
Ways to Save Money on Household Supplies
Saving on supplies is not about buying the cheapest version of everything. It is about buying the right version once.
Low-Cost Product Selection and Durability
Cheap items that fail twice cost more than one sturdy item. Before buying, check three things: the material, the load or power rating, and whether replacement parts exist. A metal organizer rated to 40 pounds beats a plastic hook that snaps in month three. Buy multi-packs only for items you use weekly: bulk paper goods make sense; a specialty cleaner you use twice a year does not.
Other reliable levers:
- Shop sales cycles and keep a running list instead of buying on impulse
- Choose refillable or concentrated versions of cleaners
- Repair before replacing when the fix costs less than a third of a new item
How to Use a Household Budget Calculator
A household budget calculator takes your income and category totals and shows what percentage each category consumes. The most common framework is the 50/30/20 rule: half of take-home pay to needs, 30 percent to wants, 20 percent to savings and debt. Enter your numbers honestly, including small purchases, then compare the output to the 50/30/20 split and adjust the flexible categories first.
Wall-Mounted Mop & Broom Organizer with 4 Hooks →
Family Size and Life-Stage Variations in Essentials
A family of two and a family of five need the same categories at very different volumes, and a household with a newborn needs a different priority order than one with teenagers. Here is how the essentials break down by household size and life stage so you can adjust the list to your actual situation rather than a generic average.
How Family Size Changes the Essentials List
The categories stay the same, but three things scale differently:
- Consumables scale with headcount. Paper goods, cleaning supplies, laundry detergent, and food rise roughly in proportion to the number of people. A family of five should expect to spend meaningfully more per month than a couple, and the budget should reflect that rather than treating it as overspending.
- Storage and organization scale with rooms, not people. One organizer per utility area or closet is usually enough regardless of family size. Buying one per person is a common overspend.
- Durable goods do not scale. One blender, one drying rack, and one basic tool kit serve the whole household. Do not buy duplicates unless the item is used simultaneously by multiple people, such as lunch containers or water bottles.
Life-Stage Priorities
Households with a newborn or infant: The priority is safety and the emergency fund.
Families with toddlers and preschoolers: Safety-minded storage matters most.
Families with school-age children: Lunch containers, water bottles, backpacks, and school supplies become recurring essentials.
Families with teenagers: Charging accessories, desk gear, and higher volumes of food and personal care items dominate.
Multigenerational homes: Space efficiency and utilities matter most.
| Family Type | Priority Essentials | Budget Focus |
|---|---|---|
| Couple, no kids | Phone stand, basic storage, reusable containers | Build emergency fund |
| Family with infants | Safe sleep space, feeding supplies, lidded diaper bin | Emergency fund and health costs |
| Family with toddlers | Anchored storage, cabinet locks, durable bins | Safety and replacement costs |
| Family with school-age kids | Lunch containers, water bottles, backpacks | Recurring school supplies |
| Family with teens | Charging accessories, desk gear, personal care items | Higher consumable volume |
| Single-parent household | Meal-prep containers, drying rack, cleaning organizer | Time-saving essentials |
| Multigenerational home | Multiple organizers, shared kitchen tools, LED bulbs | Utilities and space efficiency |
A Simple Adjustment Rule
When your household size or life stage changes, revisit three lines in your budget: consumables, storage, and durable goods. Increase consumables for a new child, add storage only if a new room or closet is in use, and avoid duplicating durable goods unless two people need the same item at the same time. That rule keeps the essentials list matched to your family without a full re-planning exercise.
Building a Realistic Starter Budget and Shopping Plan
Step 1: Total your fixed costs. Add rent or mortgage, utilities, insurance, and debt minimums.
Step 2: Set the supplies cap. Pick a monthly number for household supplies and stick to it.
Step 3: Buy the payback items first. Start with the wall-mounted organizer at $24.99, the phone stand at $12.67, then the blender or mug warmer at $29.99 each as budget allows.

Step 4: Track for 30 days. Log every purchase, then review at month end.
Step 5: Adjust and repeat. Move savings into the emergency fund.
Families rarely fail at budgeting because they lack discipline.
Frequently Asked Questions
What is the 50/30/20 rule for families?
The 50/30/20 rule splits after-tax income into three buckets: 50% for needs like housing, groceries, utilities, and insurance; 30% for wants such as dining out and entertainment; and 20% for savings and debt payments. For families, the needs bucket usually runs higher because child care and health care take a bigger share. Many households adjust to 60/20/20 or 50/25/25 and still keep the same structure. The rule works best as a starting point, then you refine it once you track actual monthly household expenses for two or three months.
Which household essentials should families prioritize in their budget?
Start with the four that keep a home running: housing (rent or mortgage plus property taxes), utilities (electricity, water, gas), groceries, and insurance. Add transportation if you commute, then child care and health care. Household supplies like cleaning products, storage, and small kitchen tools come next. A wall-mounted mop and broom organizer at $24.99 is a low-cost example of an essential that protects your tools and frees up closet space. Prioritize anything that prevents bigger repair costs later, like basic maintenance supplies and durable storage.
How can families save money on everyday household purchases?
Buy durable items once instead of replacing cheap ones repeatedly. Compare cost per use, not sticker price: a $24.99 organizer that lasts years beats three $8 versions that break. Shop sales and clearance sections, buy store-brand staples for cleaning and paper goods, and batch purchases to hit free-shipping thresholds. Track spending for a month so you know which categories drift. Also check return policies before buying, since a generous return window lowers the risk of trying a lower-priced option you have not used before.
How much should a family budget for household supplies?
Most families spend roughly 5% to 10% of their monthly budget on household supplies: cleaning products, paper goods, storage, and small kitchen or desk items. For a household spending $3,000 a month on essentials, that is about $150 to $300. Families with young children or pets usually land at the higher end. Track two months of receipts to find your real number, then set a cap. One-time buys like a $29.99 portable blender or a $12.67 phone stand should come out of a separate small-household-goods fund, not the weekly grocery run.
Can you live off $1,000 a month after bills?
It depends on what the $1,000 covers. If housing, utilities, and insurance are already paid, $1,000 can stretch for groceries, transportation, and supplies for a small family, but it is tight for a family of four in most areas. The 50/30/20 rule would put $500 toward needs, $300 toward wants, and $200 toward savings. Cut wants first, then compare essential-item costs across stores. A household budget calculator helps you test the number against your real county-level costs before you commit to it.